Synergy Roof Systems
Hail & Storm Damage Roof Repair in Houston
Hail and storm damage roof repair in Houston starts with an inspection that documents bruised or cracked shingles, dented metal, lifted tabs and other storm damage before any claim decision or repair is made. If damage is found, you may choose to file a claim with your insurance company, which sends an adjuster to assess it under your policy. Synergy Roof Systems inspects, photographs and explains the damage, can be present at the adjuster's visit to discuss the roof, and then repairs or replaces it to a written scope; coverage decisions always belong to your insurer.
Request a Storm Inspection or call (713) 510-3040.
Signs of hail or storm damage
Hail and wind damage are hard to judge from the ground, and walking a roof after a storm is dangerous. Look for these clues from a safe spot:
- Dents in gutters, downspouts, mailboxes, AC fins or patio furniture
- Dark spots on shingles where granules have been knocked loose
- Piles of granules at downspout outlets after the storm
- Shingles missing, torn or folded back on windward slopes
- Cracked skylights, vent caps or exhaust covers
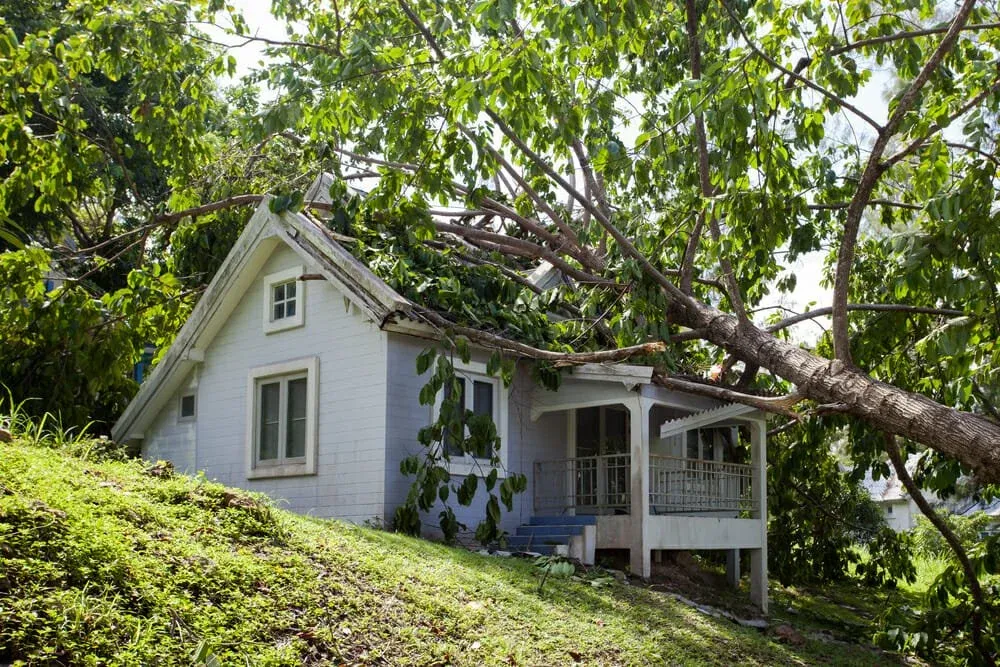
- Branches or debris on the roof, or a tree limb resting on the house
- New ceiling stains or drips after the storm passes
How insurance claims generally work
Every policy is different, so read yours and ask your insurer or agent about anything unclear. In general, a storm claim follows these steps:
- Note the date of the storm and take photos of visible damage from the ground
- Have the roof inspected so you know whether there is damage worth reporting
- Contact your insurance company to open a claim; policies set reporting deadlines, so do not wait months
- The insurer assigns an adjuster, who inspects the roof and writes an estimate
- You receive the insurer's decision, which may include payment for repairs or replacement minus your deductible
- If you disagree with the findings, your policy explains how to ask for a review or reinspection
Many Texas policies use a separate deductible for wind and hail, sometimes a percentage of the home's insured value rather than a fixed dollar amount. Check your declarations page so the number is not a surprise.
Texas law prohibits a contractor from waiving, paying or rebating a homeowner's insurance deductible, and a roofing contractor may not act as a public adjuster or negotiate the claim for you. Our role is to inspect, document the roof and answer roofing questions.
What an adjuster looks for
Adjusters assess whether the roof has storm damage covered by your policy. On a typical roof inspection they look at:
- Hail hits that bruise, fracture or puncture shingles, often counted within marked test areas on each slope
- Granule loss in a random hail pattern, as opposed to even wear from age
- Creased, torn or missing shingles that show wind damage
- Dents on vents, flashing, gutters and other metal that support the hail size and direction
- Whether the damage lines up with the reported storm date
- Pre-existing wear, prior repairs or installation issues that the policy may treat differently
We document the same items with photos and notes, so your conversation with the adjuster is based on what is actually on the roof. When it helps, we can attend the adjuster's visit to point out what we observed.
What storm repair includes and material options
Once the damage and the insurer's decision are known, the next step depends on how far the damage extends. Isolated wind damage may be a straightforward shingle repair. Widespread hail bruising across several slopes usually points toward replacement.
If you are replacing the roof, it is a good time to ask about impact-rated shingles or metal roofing for future hail seasons, and to ask your insurer whether either affects your premium.
Roof repair in Houston · Roof replacement in Houston · Metal roofing for Houston homes
Keeping good records after a storm
Good records make every later conversation easier. Write down the date and time of the storm, keep any hail photos you took with something for scale, and save the names of everyone you speak with at your insurance company along with claim numbers and dates.
Keep receipts for any emergency expenses, such as tarping or water cleanup, because some policies reimburse reasonable steps taken to prevent further damage. Store our inspection photos and report with these records so everything about the claim is in one place.
How we work
Storm work follows the same four steps as every other project.
- Inspection: we inspect the roof and attic, measure the slopes and photograph each area of damage.
- Written scope: you receive a report of findings and a written repair or replacement scope you can share with your insurer.
- Repair or replacement: work is scheduled after you approve the scope, with materials matched to the approved line items.
- Cleanup and closeout: debris and nails are cleared, and you get completion photos and paperwork your insurer or mortgage company may request.
Hail and storms in the Houston area
Spring brings much of the region's hail, when strong thunderstorms roll across the metro, but damaging hail and straight-line winds can arrive in other months too. Hurricane season, from June through November, adds the risk of sustained wind, flying debris and fallen trees.
Because storm paths are narrow, one neighborhood can be hit hard while the next sees little damage, so a professional inspection tells you more than what you hear from neighbors. After a widespread storm, be cautious of door-to-door offers that pressure you to sign right away; take time to check any contractor's local address, references and written proposal.
If a tree or limb has fallen on the house, stay out of the affected rooms and call your insurer. Do not try to remove heavy debris from the roof yourself.
Related services
- Roof Repair — Leaks, missing shingles, cracked pipe boots and loose flashing traced to the source and fixed.
- Roof Replacement — Full tear-off, decking repairs, underlayment, ventilation and new shingles or metal, all listed in a written scope.
- Roof Inspections — Photo-backed roof reports for storms, home sales and routine checkups.
- Storm Damage Response — Inspections and photo documentation after hail, wind or fallen trees.
Hail & Storm Damage near you
We work across the Greater Houston area, including:
- Houston, TX
- Pasadena, TX
- Pearland, TX
- League City, TX
- Sugar Land, TX
- Conroe, TX
- Baytown, TX
- Missouri City, TX
- Alvin, TX
- Atascocita, TX
- Bellaire, TX
- Clear Lake, TX
- Cypress, TX
- Friendswood, TX
- Fulshear, TX
- Galveston, TX
- Humble, TX
- Katy, TX
- Kingwood, TX
- Magnolia, TX
- Manvel, TX
- Richmond, TX
- Rosenberg, TX
- Spring, TX
- The Woodlands, TX
- Tomball, TX
- Webster, TX
- West University Place, TX
Request a Storm Inspection or call (713) 510-3040.
Explore Synergy Roof Systems
- Home remodeling, repairs and restoration
- Residential roofing
- Commercial roofing
- Roof maintenance
- Roof soft washing
- Fence Staining & Painting
- Metal Roofing in Houston
- Commercial Roof Repair in Houston
- TPO Roofing in Houston
- Flat Roof Repair & Replacement in Houston
- Commercial Roof Coatings in Houston
- Commercial Metal Roofing in Houston
- Roofing advice and storm tips
- Request a roofing consultation
Frequently asked questions
How big does hail have to be to damage a roof?
There is no single cutoff. Shingle age, type and condition, plus the hail's size, density and the wind behind it, all affect the result. Smaller hail can still bruise older or brittle shingles, which is why an inspection is more reliable than measuring hailstones.
Should I call my insurance company before or after an inspection?
Many homeowners have the roof inspected first so they know whether there is damage worth reporting. Check your policy for reporting deadlines, and contact your insurer promptly if you have active leaks or obvious damage.
Can you meet the insurance adjuster at my house?
Yes. We can attend the adjuster's inspection to point out the damage we documented and answer technical roofing questions. The adjuster and your insurer make the coverage decision.
Will filing a hail claim raise my premium?
That depends on your insurer and your policy. Ask your agent or insurance company directly; we do not advise on premiums or coverage.
What if the adjuster says there is no damage?
Ask your insurer for the written findings and how to request a review. Your policy describes the options available, and our photos and report show what we observed on the roof if you want to share them.